Three data points from this spring, one signal: corridor stablecoin infrastructure locks fast, and once it locks, it stays locked.
🔎 Port layer: Tether started signing port-coast exclusivity contracts with maritime operators — legal clauses that block competing stablecoins. That’s a land grab, not paranoia.
🔎 VC layer: Castle Island Ventures put money into a payments stablecoin in March. Their own research maps directly onto this thesis — regulated stablecoins in corridors where the banking system has already failed operators.
🔎 OTC layer: Virtu Financial completed a zerohash integration in May and kept expanding its stablecoin pair list. Sophisticated market makers don’t wire new infrastructure speculatively — they underwrite the demand first, then build.
Three independent actors, three layers of the same stack, moving in the same direction.
Here’s the number behind why: BALBOA1 settles at roughly $0.35 per $100. Traditional wires and correspondent banking run 2–7% on the same corridor. That gap is the actual reason infrastructure locks in this fast — it’s unit economics, not a pitch.
We’re building chain-agnostic — not locked to a single chain, designed to settle across chains as corridor infrastructure standardizes.
Tether didn’t hit $13B in annual profit by inventing the idea first. They got there by locking infrastructure before competitors showed up.
That’s the game in Panama corridor trade right now.
Author: Verra Balboa
-
The Stablecoin Infrastructure Lock-in is Already Happening
-
Balboa 1: Speeding up the Pulse of Global Commerce
Global trade relies heavily on shipping, which facilitates the exchange of goods across borders. However, the payment systems used for cross-border settlements are outdated, relying on traditional banking that is limited by operational hours, leading to inefficiencies and financial losses.
We aim to address this issue by offering a regulatory-approved stablecoin in Panama, allowing faster and more efficient international trade settlements with same-day local processing. Panama’s strategic location in global maritime trade, alongside its economic reliance on trade and logistics, positions it as a viable digital finance hub.
BALBOA 1 benefits from regulatory flexibility compared to U.S. frameworks, maintaining compliance while simplifying operations. Moreover, it ensures trust through a Real-Time Proof of Reserves mechanism, whereby each token is backed 1:1 by liquid assets in regulated banks, providing transparency and efficiency in financial transactions.
Baseline, BALBOA 1 seeks to modernize settlements, enhancing the speed of global commerce and adapting to the demands of continuous trade.
-
Stablecoin Firm BALBOA | CORP Brings Former Paxos Executive on Board
Panama-based stablecoin infrastructure company BALBOA | CORP has strengthened its advisory board by appointing former Paxos treasury executive Austin Campbell and fintech entrepreneur Richard Douglas, as it develops payment technology designed for international shipping and trade.
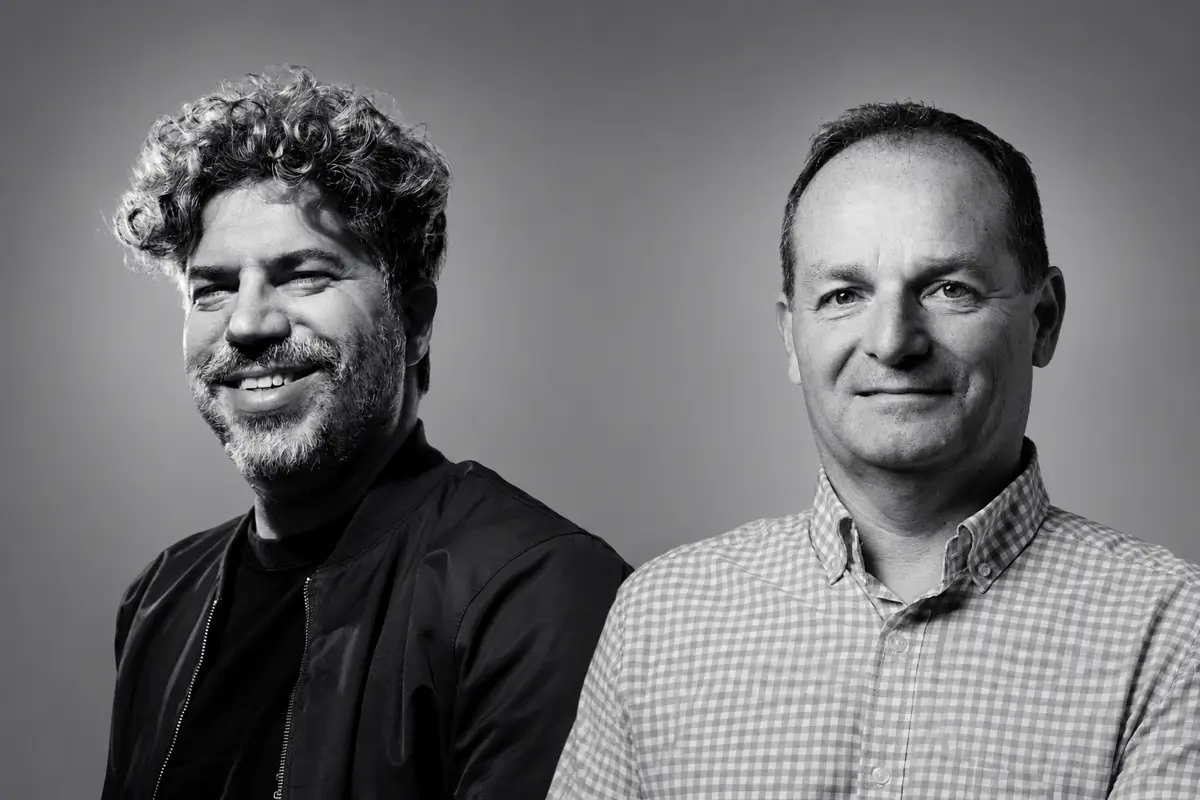
Campbell previously served as Head of Treasury at Paxos, where he managed more than $22 billion in reserves backing stablecoins and played a role in designing Binance USD (BUSD), one of the largest dollar-pegged stablecoins before it was discontinued. Earlier in his career, he held digital asset and trading positions at JPMorgan, Citi and Stone Ridge. Today, Campbell leads consulting firm Zero Knowledge Group, advising banks, asset managers and payments companies on digital asset strategies.
Richard Douglas, who also joins BALBOA | CORP’s advisory board, is a three-time fintech founder with experience in payments, risk management, compliance and financial technology governance. His background includes advising blockchain and payments businesses on regulatory and operational risks.
BALBOA | CORP said the new appointments will help support the development of BALBOA1, its U.S. dollar-backed stablecoin created for business-to-business trade payments. Rather than focusing on consumer crypto transactions, the company aims to use blockchain technology to reduce delays in international settlements between buyers, sellers and shipping companies.
Cross-border trade often relies on multiple banks, payment providers and manual verification processes, which can take several days before funds become available. These delays may increase financing costs and contribute to demurrage fees, i.e. charges paid when cargo remains at ports longer than agreed because documentation or payments have not been completed.
According to BALBOA | CORP, BALBOA1 is designed to provide near real-time settlement while supporting escrow arrangements and trade finance workflows. The company says the stablecoin will operate on Ethereum, with each token backed 1:1 by U.S. dollars held with trust or partner banking institutions.
Kevin Conabree, co-founder and CEO of BALBOA | CORP, said the appointments combine expertise from both traditional banking and digital assets, helping the company build infrastructure suitable for institutional trade finance.
Campbell said he believes the platform addresses longstanding payment delays in global trade while offering institutions a programmable digital dollar for commercial use. Douglas added that synchronizing cargo movements with digital payments could help reduce operational costs while supporting regulatory compliance.
The announcement reflects a broader shift in how stablecoins are being used. Initially popular for cryptocurrency trading, stablecoins are increasingly being tested for corporate treasury operations, international settlements and trade finance because they can move funds around the clock without relying on traditional banking hours.
The stablecoin market has grown rapidly over the past two years, with the total circulating supply now exceeding $300 billion, led by Tether’s USDT and Circle’s USDC. Industry analysts increasingly view stablecoins as an emerging payment infrastructure rather than simply crypto assets, with banks, payment companies and governments exploring their role in modernizing cross-border transactions. Meanwhile, institutional adoption continues to expand following regulatory developments such as the U.S. GENIUS Act and Europe’s Markets in Crypto-Assets (MiCA) framework, both of which are expected to provide greater legal clarity for digital dollar payments.
-
Volatility is a Balance-Sheet Problem for Banks
Volatility Is a Balance-Sheet Problem for Banks
For retail traders, volatility can create opportunity. For banks, treasury desks, and cross-border trade finance, volatility can create something very different: principal risk.
Consider a bank facilitating a $50 million cross-border transaction.
If the settlement asset moves 3% during the settlement window, the economic value at risk can be significant—before accounting for liquidity, hedging, capital, and operational considerations.
Institutional transaction banking therefore requires more than speed. It requires:
➡️ Value stability
➡️ Predictable liquidity
➡️ Capital preservation
➡️ Operational certainty
This is a fundamental reason why BALBOA1 is designed around 1:1 USD reserve backing. The objective is to create a settlement instrument that combines the efficiency of distributed ledger technology with a value structure designed for commercial transactions—without exposing every settlement to the price volatility associated with conventional cryptoassets.
That distinction matters.
Banks don’t necessarily need another asset to speculate on.They need better infrastructure for moving value. If digital settlement can deliver blockchain speed while maintaining a stable-value architecture, the opportunity extends far beyond crypto trading. It reaches into transaction banking, treasury management, cross-border payments, and global trade finance.
Speed matters. But for institutional finance, speed with value stability matters more. -
This Model Already Works at $6.5. Maritime and Trade Finance have No Equivalent.
Zeebu settled $6.5 billion in B2B invoices between wholesale telecom carriers using stablecoins. 5-day payment cycles reduced to 30 minutes. 50% cost reduction. 140 carriers.
TCS integrated PYUSD to offer same-day freight invoice settlement for trucking carriers. On track for $1 billion in annual freight invoice volume. 90% cheaper than traditional invoice factoring.
Both solved the same structural problem: recurring bilateral relationships between known counterparties, USD-denominated invoices, multi-day settlement delays causing working capital drag.
Maritime trade has the same structure.
$30 billion per year in demurrage — penalty charges when cargo sits at port waiting for a SWIFT wire to clear. $20K–$80K per vessel per day. 42-day average invoice payment cycle. $270 billion in annual cargo through the Panama Canal alone.
BALBOA1 settles at roughly $0.35 per $100 moved — a fraction of the 2–7% traditional wires and correspondent banking charge on that cargo.
The ocean freight equivalent of what Zeebu built in telecom and TCS built in trucking has not been funded.
Not because the model hasn’t been proven — two industries have proved it. Not because the demand doesn’t exist — the demurrage numbers confirm it. Because maritime corridor settlement requires physical presence (a Panama S.A. entity, ship agent relationships, ACP compliance) that a software company can’t replicate from a laptop.
The model is established. The corridor is vacant. That’s the build. -
Why Banks Have Stayed on the Sidelines of Crypto — and the Infrastructure Case for Change
Why do tier-one banks continue to hesitate on crypto rails?
It isn’t a lack of interest in blockchain technology. It’s a matter of institutional risk management.
When bank risk committees evaluate standard digital assets, they face three major structural brick walls:
1️⃣ Capital Penalties: Under Basel rules, unbacked crypto assets incur a 1,250% risk weighting. Holding these requires dollar-for-dollar capital reserves, making balance-sheet exposure unviable.
2️⃣ Compliance Risks: Permissionless networks create direct friction with Bank Secrecy Act (BSA) and OFAC sanctions enforcement.
3️⃣ Custody & Legal Liability: Without clear jurisdiction and bankruptcy-remote custody, holding digital assets presents unquantifiable legal exposure.
For digital rails to achieve institutional adoption, the underlying infrastructure must be redesigned to fit banking requirements—not the other way around.
That is why BALBOA CORP developed BALBOA1:
• 1:1 USD reserve backing to remove volatility
• Built-in KYC/KYB gating and dual-record auditability
• Bank-grade escrow structures for programmable legal finality
• Anchored in Panama’s global trade and banking jurisdiction.
Digital speed doesn’t have to mean regulatory compromise. -
LATAM Banks Aren’t Blocking Stablecoins — They’re Panicking
71% of Latin American financial institutions use stablecoins for cross-border payments — the highest regional adoption rate globally.
LATAM stablecoin flows reached 7.7% of GDP in 2024, the highest of any region worldwide, per IMF research. Traditional wire fees run 3–7%. Stablecoin settlement typically costs under 1% — BALBOA1 settles at roughly $0.35 per $100 moved.
The shift is not coming. It’s underway.
BALBOA1 is designed as infrastructure for institutional trade finance operators in this environment — specifically for the maritime trade corridor through Panama. Not a consumer wallet. Not a remittance layer. The regulated settlement rail for the counterparties that move goods and capital through the Canal Zone.
For financial institutions evaluating stablecoin infrastructure for their trade finance clients: the corridor-specific model is the entry point that doesn’t require building from scratch. -
The Document Layer and the Payment Layer are not the Same Problem
Those who say “maritime trade digitization will take decades” are looking at the document layer. 📄
They are right. Electronic bill of lading (eBL) adoption recently hit 10–15% globally — up from under 3% in 2022, with the first cross-platform interoperable eBL transaction completed in January 2026. Major carriers like Maersk, MSC, and CMA CGM all support it now, with industry projections pointing to 50% adoption by 2028.
That represents real progress on a decades-long document digitization project.
However, BALBOA1 does not need eBL adoption to function.
An eBL tells stakeholders who owns the cargo, while a stablecoin settlement pays for moving it. One is a document; the other is money. They are parallel digitization tracks, not sequential ones.
TCS/PYUSD is settling $1B+ in trucking freight invoices in 2026, on a same-day basis. Trucking does not rely on eBLs — it uses paper waybills. Payment digitization ran ahead of document digitization by years in that sector, and the same dynamic applies to maritime trade.
The 42-day average maritime payment cycle is not caused by paper eBLs. It is caused by SWIFT — correspondent banking holds, rigid banking hours, and manual compliance checks. A perfectly digitized eBL on DCSA standards still clears payment in 42 days if the underlying rail remains SWIFT.
BALBOA1 settles corridor payments for roughly $0.35 per $100 moved — a fraction of the 2-7% correspondent-banking cost baked into that 42-day cycle. BALBOA1 solves the payment track today, allowing the document track to catch up on its own timeline. -
Mexico Built a Canal Competitor. That Makes BALBOA1’s Market Better.
Mexico’s Interoceanic Corridor of Tehuantepec is now operational — 303 km of rail connecting Pacific to Gulf. A pilot moved 900 vehicles in 9 hours, 5 days faster than the Panama Canal route.
Analysts are calling it a threat to Panama. The structural reality tells a different story.
The Tehuantepec Corridor can handle containerized goods, vehicles, and light manufactured products. What it cannot handle: supertankers, LNG carriers, bulk cargo ships, or anything that physically requires a water route.
The Panama Canal isn’t competing for the same cargo.
The ACP’s own toll structure confirms the strategy. LNG tariffs are up 200% over three years. Container tariffs are up 12.5% per TEU. The Canal is deliberately pricing up the traffic it wants to retain — high-value, large-vessel, hard-to-reroute — while accepting that light containerized cargo migrates to cheaper alternatives.
Mexico’s rail corridor is giving the ACP what it wants: price-sensitive traffic off the Canal, leaving behind the high-margin transits that generate $840K+ in fees per vessel.
For BALBOA1, the Canal’s remaining traffic post-Tehuantepec is higher-value and more payment-friction-intensive. Operators running billion-dollar LNG tankers through the Canal on SWIFT wires are exactly the clients with the most to gain from same-day programmable settlement.
The Strait of Hormuz disruption since February 2026 is compounding the same trend from a different direction. Tanker and LNG traffic rerouted away from the Middle East pushed Canal transits toward 40 vessels a day against a 36-vessel design capacity, and auction slot prices went from roughly $135K–$140K pre-conflict to as high as $4 million for a single slot by May 2026. Two independent forces — Mexico pulling light cargo out, Hormuz pushing high-value cargo in — are filtering the Canal toward the same conclusion: fewer, bigger, higher-friction transactions.
The market doesn’t shrink. It deepens. -
Three Companies Solving Trade Finance at Three Different Layers. None Competing.
Three companies touch stablecoins in trade finance, yet venture capitalists frequently cite them as direct competitors. They are not—and recent market shifts make the distinction even sharper.
➡️ Contour: Originally launched as the flagship bank-consortium bet on digitizing Letters of Credit, backed by HSBC, Standard Chartered, Citi, and DBS. It shut down in 2023 and changed hands twice before XDC Ventures relaunched it in October 2025. Crucially, it did not return as an LC platform, but as a stablecoin settlement rail. A company built to prove the document layer could scale ultimately survived by leaving the document layer entirely.
➡️ Goldfinch: Focuses on uncollateralized RWA credit for emerging market businesses, deploying $170M+ across 28 countries within a broader $12B+ RWA credit ecosystem alongside Maple and Centrifuge. Its product provides the capital to finance the trade before invoice settlement.
➡️ BALBOA1: Settles the actual invoice between the freight forwarder and the ship agent, the Canal toll between the vessel operator and the ACP, and the bunkering fee between the shipowner and the fuel supplier. Operating with named counterparties across a single corridor, its product is the physical movement of cash when goods move—costing roughly $0.35 per $100 moved, compared to the 2–7% traditional correspondent-banking wires it replaces.
Contour’s trajectory illustrates this reality clearly: the instrument layer lacked the volume required to sustain the platform, whereas settlement provided the viable path forward.
The argument that platforms like Contour have “already solved trade finance” overlooks a pivot that ultimately aligns with BALBOA1’s premise. While previous models abandoned the instrument layer, BALBOA1 was built purely for settlement from the start.